What Is Probate Value and Why Does It Matter for CGT? Emmanuel Akyeam October 6, 2026 What is probate value and why does it matter for CGT? It sets the base cost for inherited assets. See…
What Is Taper Relief and Does It Still Apply to UK Capital Gains Tax? Emmanuel Akyeam October 5, 2026 Taper relief was abolished for UK Capital Gains Tax in April 2008. Learn how it worked, what replaced it, where…
Capital Gains Tax When You Sell Your Home in the UK: Complete 2026 Guide Emmanuel Akyeam July 20, 2026 A private residential property disposal in the United Kingdom representing your primary family home is legally shielded from taxation
How Long Do You Have to Live in a Property to Avoid CGT UK? Emmanuel Akyeam July 20, 2026 An analysis of historical tax tribunal cases reveals that HMRC regularly challenges claims for Private Residence Relief where
What Is Private Residence Relief? CGT Exemption Explained Emmanuel Akyeam July 20, 2026 What is Private Residence Relief? It is the tax rule that can turn a residential property sale with
Capital Gains Tax for Married Couples and Civil Partners UK Emmanuel Akyeam July 16, 2026 Capital Gains Tax for married couples and civil partners works differently to how most people expect. HMRC does
Can I Use Capital Losses to Reduce My CGT Bill? Emmanuel Akyeam July 16, 2026 Yes – using capital losses to reduce my CGT bill is one of the most effective and legitimate
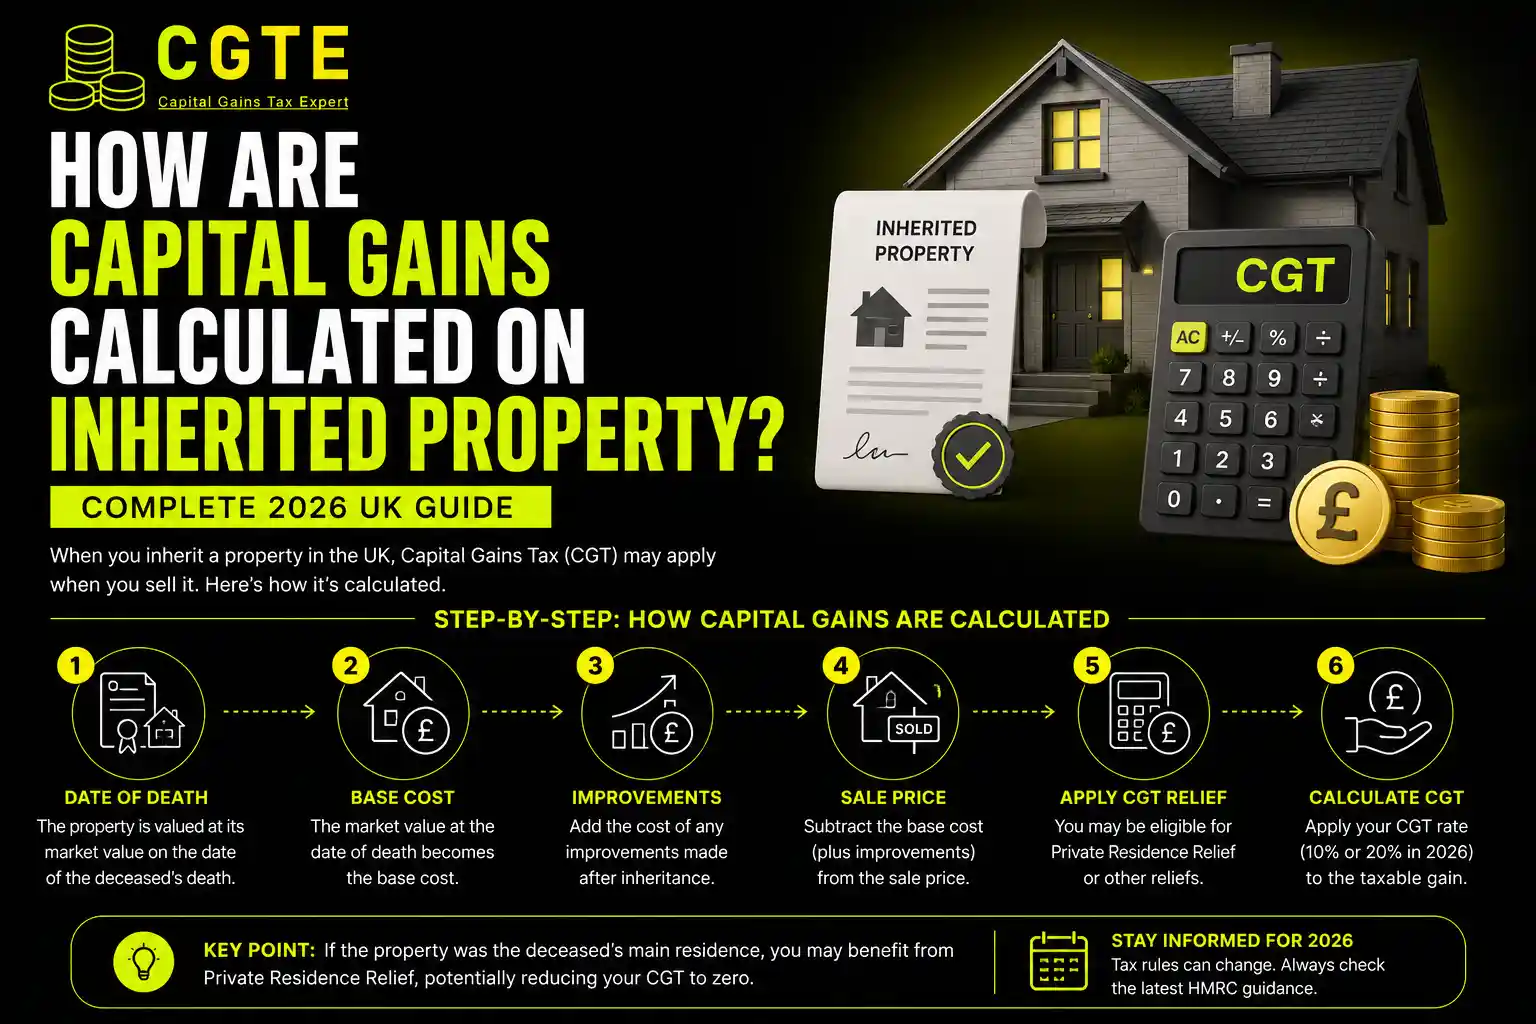
How are capital gains calculated on inherited property? Complete 2026 UK Guide Emmanuel Akyeam June 29, 2026 Probate values are the cornerstone of how are capital gains calculated on inherited property in the UK and most beneficiaries
Do you need to pay Capital Gains Tax on an inherited property? Emmanuel Akyeam June 1, 2026 The inheritance of a property is a major financial milestone, yet it frequently brings unexpected tax complexities that
What is the Little Known Loophole for Inheritance Tax and Capital Gains Tax Emmanuel Akyeam May 14, 2026 There is no single little known loophole in UK inheritance tax. The real planning opportunities are strict statutory exemptions and